.
필리핀은 산업화 측면에서 다른 동남아시아 국가들에 비해 분명히 뒤처져 왔다. 마리카르 피에다드(Maricar Piedad)는 필리핀의 제조업이 ‘저발전에 갇혀 있다’고 설명했다. 20세기 중반까지 제조업이 역사적으로 높은 성장률을 보였음에도 필리핀의 산업은 생산을 늘리는 데 실패했기 때문이다. 1970년대에 이르러 한국과 대만, 동남아시아 일부 지역의 수출이 급증하고 이들 지역의 제조업체들이 기술을 고도화하는 동안, 필리핀 제조업의 성장률은 하락했다. 그 중심에는 1970년대 후반부터 필리핀 산업의 지속적인 후퇴를 초래한 필리핀 정부의 실책이 자리한다.
그러나 필리핀 정부는 다시 산업화로 방향을 돌리고 있으며, 역설적이게도 이를 이끄는 것은 마르코스 주니어(Marcos Jr.) 정부다. 그의 아버지인 마르코스 전 대통령의 정책들이 필리핀 제조업의 둔화를 초래했던 반면, 마르코스 주니어 정부는 산업화를 끝까지 추진하려는 의지가 더 확고한 것으로 보인다. 필리핀 정부는 세계적인 지정학적·경제적 변화, 공급망 재편, 인공지능의 급속한 성장, 녹색경제로의 전환, 그리고 자국이 관리·통제하는 핵심광물 자원이 제시하는 잠재적 가능성을 인식하고, 이러한 변화와 자국의 자산을 유리하게 활용하고 있는 것으로 보인다.
이 글은 필리핀 산업화의 역사와, 1970년대 이후 필리핀 국가가 내린 부실한 정책 결정들이 어떻게 산업화를 가로막아 산업화된 국가가 되려는 시도에 심각한 영향을 미쳤는지를 추적한다. 필리핀은 노동력의 해외 송출을 확대해 경제를 지탱하는 데 성공했지만, 역설적으로 이는 산업 기반을 약화시켰다. 2000년대에 이르러 반도체 산업을 통해 산업화를 추진하려는 노력이 강화되었다. 그러나 국가 정책과, Piedad (2026)가 지적한 외국인 투자 주도 산업화에 대한 과도한 의존으로 인해 필리핀은 전통적인 조립·검사·패키징에 머무르면서 글로벌 가치사슬의 하단에 남아 있었다. 마지막으로 이 글은 글로벌 가치사슬에서 필리핀의 위치를 재정립하려는 현 행정부의 노력과, 필리핀이 다음 산업화 기회마저 잃게 만들 수 있는 잠재적 함정들을 검토한다.
잘못된 경제 정책이 초래한 필리핀 산업화의 둔화
이웃 국가들에 비해 상대적으로 탄탄한 제조업 기반, 교육받고 영어를 구사하는 노동자층, 그리고 당시 세계 최대 경제였던 미국 시장에 대한 우대 접근권은 한때 필리핀이 역내 제조업 강국으로 성장할 수 있는 여건을 제공했다(Masina, 2026). 필리핀 제조업은 20세기 초반부터 중반까지 높은 성장률을 기록하여 다른 국가들과의 제조업 격차를 줄일 수 있었다(Williamson and de Dios, 2014). 그러나 1970년대부터 1990년대까지 아시아 여러 지역의 제조업이 급성장하는 동안에도, 필리핀의 산업 부문은 해당 기간에 성장이 미미하거나 거의 없는 심각한 정체를 겪었다. 이 부문의 고용 증가 역시 현저히 정체되었다. 따라서 동남아시아와 동아시아 여러 지역에서 산업화가 심화되는 동안 필리핀의 산업화는 정체되었다.
필리핀에서 산업화가 본격적으로 진전되지 못한 데에는 많은 이유가 있으며, 이는 다른 문헌들에서 충분히 논의되어 왔다. 그 중에는 1970년대 필리핀의 정치·경제적 불안정도 포함된다. 그러나 세계경제에 서비스 노동을 제공하는 방향으로의 전환 역시 제조업이 오랫동안 정체된 이유 중 하나였다. Masina (2026)에 따르면 필리핀의 노동 이주 정책은 산업화를 희생한 대가로 이루어졌다. 노동 이주로 발생한 소득과 외화는 경쟁력 있는 제조업 기반을 구축하려는 유인을 약화시켰다. 노동자들의 해외 이주로 노동 공급은 줄어들고 송금은 늘어났다. 임금이 생산성보다 빠르게 상승하면서 국내 제조업체 수가 감소했다. 더욱이 산업 기반을 구축하는 데에는 많은 자본이 필요했다. 이를 위해서는 투자와 투자자를 전략적으로 동원해야 했으며, 다른 동남아시아 국가들에 비해 경쟁우위를 확보해야 했다. 경제를 지탱하는 일이 절박했던 필리핀은 국내 제조업과 고용을 강화하기보다 노동력 수출에 더 많이 투자하는 비전형적인 경로를 택했다. 일부 아시아 및 라틴아메리카 국가들이 그랬던 것처럼 송금액을 수출 제조업 부문에 재투자할 수도 있었지만, 필리핀에서는 이주민과 그 가족들이 송금액을 소비재와 서비스, 부동산에 투자했다.
코라손 아키노(Corazon Aquino)와 그 뒤를 이은 행정부들은 국가의 노동력 수출 정책과 관련 산업을 강화했다. 이 정책은 매우 성공적이어서 이주정책연구소(Migration Policy Institute, 2008)가 ‘개발도상국 세계의 다른 어느 곳에서도 견줄 수 없는’ 것으로 묘사한 규모의 이주를 만들어냈다. 이주정책연구소는 일시적 이주를 관리하는 필리핀의 이주 체계를 ‘정교함에서 견줄 상대가 없는’ 체계로 묘사했으며, ‘다른 개발도상국의 모범’이라고도 평가했다. 수년 동안 필리핀 경제는 해외 계약 노동자들이 본국으로 보내온 수십억 달러의 송금으로 지탱되었다. 노동 이주는 국내 노동시장이 흡수하지 못한 고학력 인구에게 일자리를 제공했으며, 수많은 필리핀인의 소득을 향상시켰다. 다시 말해, 필리핀의 이주 노동자들은 산업 기반이 없는 상황에서도 경제를 지탱하며 필리핀 경제의 발전에 기여했고, 필리핀 가정들을 중간소득 계층으로 끌어올렸다. Masina가 지적하듯 필리핀 경제는 붕괴하지 않았고, ‘장기적인 정체도 없었으며’, ‘급격한 경제 붕괴’도 없었고, ‘경제는 안정되었다’. 이로 인해 해외 이주는 국가의 고용·경제 정책으로서 더욱 매력적이고 실행 가능한 것으로 보이게 되었다.
이주가 경제에 기여했음에도 진보적 집단들은 필리핀 국가의 이주 정책을 비판해 왔으며, 이주에 기반한 국가 발전 정책이 국내 경제를 발전시키는 데 실패했다고 주장했다. 한국과 대만, 말레이시아, 태국, 베트남이 생산성을 높이는 수출 지향 제조업 부문을 구축한 반면, 필리핀 경제의 성장은 주로 노동력의 유입과 송금이 촉진한 소비에 기반해 왔다. 따라서 필리핀 경제의 성장은 낮은 생산성을 특징으로 했다. 경제 발전 전략으로서 이주 정책이 지닌 균열은 전 세계적인 코로나19 팬데믹이 시작되면서 뚜렷해졌다. 팬데믹으로 200만 명이 넘는 필리핀 해외 노동자(OFWs, overseas Filipino workers)가 귀국해야 했으며, 이는 필리핀 경제에 부정적인 영향을 미쳤다. 이주민의 본국 귀환과 해외 노동시장의 폐쇄는 필리핀 관료들에게 이주가 세계적인 충격에 취약한 성장 전략이라는 사실을 뼈아프게 깨닫게 했다. 송금액은 높은 수준을 유지했지만, 정부가 귀환 노동자들을 위한 일자리를 만들어내지 못하면서 국내 고용의 대안으로서 이주가 갖는 한계가 드러났다. 송금과 그것이 경제에 기여하는 바에 대한 과도한 의존은 필리핀이 보다 안정적인 국민소득의 원천이 될 제조업 기반을 구축하는 데 성공하지 못했음을 분명히 보여주었다.
반도체 산업의 함정
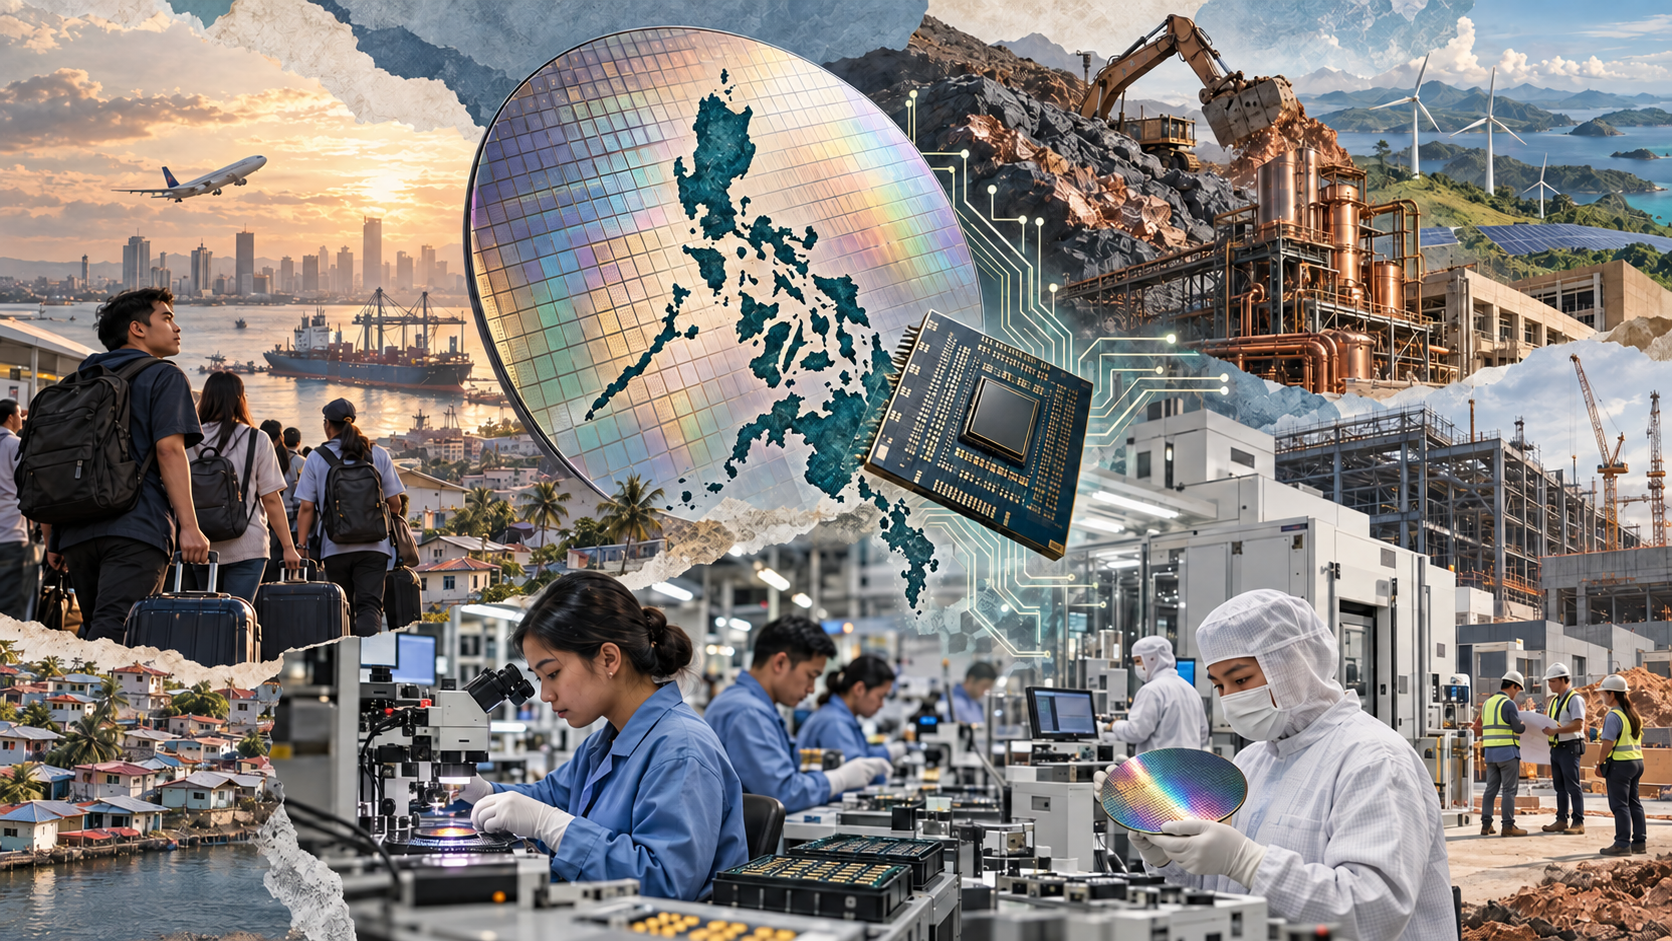
필리핀의 반도체 산업은 이르면 1970년대에 페어차일드(Fairchild), 인텔(Intel), 텍사스 인스트루먼트(Texas Instruments), 앰코(Amkor)의 후공정 생산시설이 필리핀으로 이전하면서 시작되었으며, 이를 통해 필리핀은 아시아의 중요한 전자제품 제조 허브가 되었다. OECD (2024)에 따르면 이들 기업의 국내 사업은 필리핀을 글로벌 전자제품 공급망에 편입시켰다. 이 기간 동안 필리핀의 반도체 산업은 외국인 직접투자에 의존해 왔으며, 미국·한국·서유럽 기업들이 주요 투자 주체였고 대만과 일본에서 유입되는 투자도 늘어나고 있다. 현재 필리핀에서 자회사를 운영하는 글로벌 기술 대기업으로는 미국의 텍사스 인스트루먼트, 온세미(onsemi), 아날로그 디바이스(Analog Devices), 앰코 테크놀로지(Amkor Technology), 유럽의 ST마이크로일렉트로닉스(STMicroelectronics)와 넥스페리아(Nexperia), 그리고 한국의 SFA반도체(SFA Semicon)가 있다.
이러한 외국인 직접투자(FDI)는 필리핀에 수십억 달러의 투자를 가져왔다. 또한 OECD 보고서(2024)에 따르면 반도체 제품이 필리핀 상품 수출의 상당 부분을 차지하면서 필리핀은 세계 9위의 반도체 수출국이 되었다. 그럼에도 이것이 산업화로 이어지지는 않았다. 실제로 필리핀 제조업은 국내 공급업체 및 산업과의 연계가 제한적이라는 점에서 ‘얕다’는 비판적인 평가를 받아 왔다(Piedad, 2026).
필리핀은 글로벌 공급망의 말단에 머물러 있다. 국내 산업 주체들이 고부가가치의 상류 단계나 중류 단계의 생산에 참여하는 대신, 조립·검사·패키징(Assembly, Testing, and Packaging, ATP)에만 관여하기 때문이다. 상류 단계의 생산은 지식 집약적 생산을 포함하며, 중류 단계의 생산은 반도체 제조를 포함한다. 산업 이익의 대부분은 이 두 단계에 집중된다. 상류 단계의 생산은 미국과 영국, 대만, 한국, 중국 같은 세계적인 주요 국가들이 독점하고 있다. 동남아시아에서는 싱가포르가 대만, 한국, 중국 등과 함께 중류 단계의 제조 국가 대열에 합류해 있다. 말레이시아와 필리핀, 태국, 베트남 같은 동남아시아 국가들은 모두 하류 단계의 생산에 집중되어 있으며, 그중 말레이시아가 역내에서 가장 높은 시장점유율을 보인다. 필리핀은 글로벌 가치사슬의 상류·중류 단계 생산자들이 제공하는 지식과 자본에 기반한 가치 대신, 노동에 기반한 가치만을 제공해 왔다. 안타깝게도 필리핀은 반세기 동안 이 산업에 참여해 왔음에도 말레이시아와 베트남에 경쟁우위를 잃어가고 있다.
필리핀은 지난 50년간 반도체 다국적 대기업들을 유치해 왔지만, 생산 과정에서 상위 단계로 이동할 수 있게 해주는 기술 이전은 이루어지지 않았다. 인텔이 35년간의 사업을 마치고 필리핀에서 철수했을 때에도 필리핀은 자국의 전자산업을 구축할 수 있게 해주는 기술 이전의 혜택을 얻지 못했다(Jarabe, 2026; Africa, 2026). 텍사스 인스트루먼트 역시 1970년대부터 더 높은 부가가치의 생산에 투자하는 대신 사업을 ATP에 한정해 왔다(Africa, 2026). 필리핀에서 사업을 운영하는 33개 반도체 기업 가운데 필리핀 자본이 소유한 기업은 두 곳뿐이다(Jarabe, 2026). 이처럼 국내 소유가 제한적이라는 사실은 필리핀 반도체 산업의 취약성을 드러내며, 이 산업이 얕은 산업화만을 낳았다는 비판을 뒷받침한다. 더욱이 필리핀 반도체·전자산업재단(Semiconductor and Electronics Industries in the Philippines Foundation, Inc.) 회장인 빙 비에라(Bing Viera)에 따르면, 국내에서 생산되는 제품은 다른 국가들도 쉽게 생산할 수 있는 저부가가치 제품이다. 이 산업은 필리핀 기업을 중심으로 탄탄한 산업 기반을 구축하기보다 외국인 투자에 크게 의존해 왔다. 이는 이윤이 여전히 자사 사업의 방향을 결정하는 다국적기업들의 수중에 집중되어 있음을 뜻한다.
필리핀 정부가 국가 주도형 발전 전략을 채택하지 못한 결과, 외국인 투자에 의존하는 경제 전략이 자리 잡았다. 이는 외국인 직접투자에 의존하기보다 자국 산업을 구축하고 지원하는 데 집중해 온 한국 같은 국가들의 산업화 전략과 뚜렷한 대조를 이룬다. 한국은 다국적기업의 외국인 투자를 선별적으로 제한하고, 자국 산업을 뒷받침하기 위해 기술 도입과 역설계를 실시했다. 역내 다른 국가들 역시 자국을 제조업 허브로 전환하기 위해 국가주의적 계획을 추진하는 등 유사한 전략을 따랐다. 이와 달리 필리핀의 반도체 산업은 생산을 지원할 다른 국내 기업들을 육성하는 촉매 역할을 하지 못했다(Aldaba and Aldaba, 2010). 국내 기업들의 경쟁력이 약하고 기술이나 지식 이전을 흡수할 능력이 부족했기 때문에 외국인 직접투자의 국내 기업에 대한 파급효과는 미흡했다. 또한 수출가공 모델은 제조업체들이 원자재를 수입하고 가용한 현지 노동력을 활용한 뒤 생산된 상품을 수출하는 고립된 생산 거점을 만들어냈으며, 이로 인해 국내 기업과 협력할 여지는 거의 남지 않았다.
산업화의 전망과 잠재적 함정
잘못된 국가 정책과 일관된 산업 전략의 부재로 과거의 산업화 기회들을 놓쳤던 필리핀은, 특히 지난 10여 년간 세계무역과 글로벌 가치사슬이 급속히 변화하면서 자국 경제사의 중대한 시점에 서 있다. 베니그노 아키노 3세(Benigno Aquino III) 대통령과 그의 후임자들은 지속적인 경제성장을 보장하기 위한 산업화의 중요성을 인식하고 더욱 명확한 산업화 의제를 제시했다. 예를 들어 아키노는 ‘제조업·농업·서비스업의 통합, 공급망의 공백 해소, 글로벌 가치사슬에 대한 산업의 참여 심화’를 담은 ‘종합 국가 산업 전략(Comprehensive National Industrial Strategy, CNIS)’을 수립했다. 이후 두테르테(Duterte) 정부는 CNIS의 일부 목표를 계승하고 이를 확장한 포용적 혁신 산업 전략(Inclusive Innovation Industrial Strategy)을 출범시켰다. 한편 마르코스 주니어 정부는 2024년 타탁 피노이법(Tatak Pinoy Act)을 통과시킨 뒤 2025년 타탁 피노이 전략(Tatak Pinoy Strategy)을 출범시켰다. 이는 2025년부터 2040년까지 시행되는 야심찬 프로그램으로, 정부와 민간 부문의 노력을 조율하여 필리핀 산업의 글로벌 경쟁력을 향상시키고, 국내 산업이 글로벌 가치사슬에서 상위 단계로 이동하도록 촉진하며, 국내 기업들이 다양하고 고도화된 제품과 서비스를 제공할 수 있도록 지원하는 것을 목표로 한다.
마르코스 정부의 산업화 정책을 가늠하는 시험대는 팍스 실리카다. 이는 미국과 미국이 신뢰하는 동맹국들 사이에 기술 공급망을 구축하고 강화하려는 미국 주도의 구상이다. 미국과 필리핀 정부는 2026년 4월 16일 이 협정에 서명했다. Geducos and Hernando-Malipot (2026)에 따르면 필리핀의 역할은 타를라크(Tarlac)의 뉴클라크시티(New Clark City)에 ‘반도체, 인공지능, 첨단 제조업, 핵심광물 가공 활동’을 유치하는 것이다. 계획된 협력은 필리핀이 가공되지 않은 핵심광물 공급국이라는 전통적인 역할에서 벗어나 첨단 고부가가치 제조업 허브로 전환하고 글로벌 가치사슬 내 입지를 강화함으로써 산업화를 촉진할 것으로 구상되고 있다. 마르코스는 팍스 실리카 산업 허브를 핵심광물 공급과 가공, 반도체 제조, 첨단 제조업, 청정에너지 기술, 인공지능 및 디지털 인프라를 포함한 기술 공급망 전반에 걸친 통합 제조 생태계로 구상하고 있다. 이 허브는 배터리의 중요한 원료인 구리·니켈·아연 등의 광물 공급을 지원하고, 단순한 채굴을 넘어 광물 원료의 정제와 가공을 지원하게 될 것이다.
이러한 구상들은 반도체 산업이 필리핀의 산업화를 심화시킬 수 있는 생산적인 국내 생태계와 단절되어 있다는 기존의 비판에 대응한다. 타탁 피노이와 팍스 실리카는 필리핀 노동이 노동에 기반한 가치뿐 아니라 지식에 기반한 가치도 제공하도록 전환하겠다는 약속도 담고 있다. 그러나 협상의 핵심적인 부분들은 현재까지도 진행 중이다. 필리핀 정부는 현지화 요건을 관철하고, 기술 이전과 공동연구를 확보하며, 국내 기업을 고부가가치 기능에 참여시켜야 한다(Balaoing-Pelkmans, 2026). 그렇지 않고 유리한 협정을 확보하는 데 실패한다면 필리핀은 산업화 경쟁에서 다시 한번 따라잡는 데 실패할 것이다. 모든 것이 여전히 협상 중이고 현재 이용할 수 있는 모든 자료가 이 사업에 관한 상투적인 설명만을 담고 있기 때문에, 이것이 필리핀의 산업화 추진에 어떤 영향을 미칠지 말하기에는 아직 너무 이르다. 정부가 협상에서 유리한 조건을 확보한다면 팍스 실리카는 산업화의 중요한 촉매가 될 수 있다. 반대로 그러지 못하면 과거의 중대한 정책 실패를 되풀이할 수 있다.
Playing Catch-up in the Industrialization Game: Problems, Pitfalls, and Prospects in the Philippines
The Philippines has unquestionably lagged behind other Southeast Asian nations in terms of industrialization. Philippine manufacturing has been described by Maricar Piedad as “stuck in underdevelopment,” with the failure of Philippine industries to increase their production despite historically strong growth rates in manufacturing up to the mid-20th century. By the 1970s, while exports of South Korea, Taiwan, and parts of Southeast Asia surged and manufacturers there upgraded their technologies, the growth rate of Philippine manufacturing declined. Central to this are the ill-conceived policies of the Philippine Government that have contributed to the steady regression of the Philippine industry since the late 1970s.
However, the Philippine Government is pivoting back toward industrialization led, ironically, by the Marcos Jr. Government. While his father’s policies led to the slowdown of Philippine manufacturing, the Marcos Jr. Government appears to be more resolute in seeing industrialization through. Realizing the potentials presented by global geopolitical and economic shifts, the restructuring of supply chains, the accelerated growth of artificial intelligence, the transition toward a green economy, and the country’s stewardship and control over critical mineral resources, the Philippine state appears to be leveraging these changes and its assets to its advantage.
The article will trace the history of Philippine industrialization and how this was curtailed by weak policy decisions made by the Philippine State from the 1970s onwards, which severely impacted the country’s bid to become an industrialized nation. The country invested in labor migration, which succeeded in keeping the economy afloat, but which paradoxically weakened its industrial base. By the 2000s, increased efforts were made to industrialize through the semiconductor industry; however, state policies and what Piedad (2026) calls the country’s overreliance on foreign investment-led industrialization have kept the country at the lower end of the global value chains, remaining in traditional assembly, testing and packaging. Lastly, it will examine the current Administration’s efforts to re-position the Philippines in the global value chains, as well as the potential pitfalls that could cost the Philippines its next shot at industrialization.
Flawed Economic Policies lead to the Slow
The relative robustness of the Philippines’ manufacturing base compared to its neighbors, its educated and English-speaking class of workers, and its preferential access to the American Market—then the biggest economy in the world—once poised the country to become a manufacturing powerhouse in the region (Masina, 2026). The Philippine manufacturing industry experienced significant growth rates in the early to mid-20th century that allowed it to reduce its manufacturing gap compared to other countries (Williamson and de Dios, 2014). However, from the 1970s to the 1990s, the industrial sector experienced serious stagnation with marginal to no growth being observed during the period, even as manufacturing in many parts of Asia was surging. Employment in the industry had also stalled significantly. Thus, while industrialization deepened in many parts of Southeast and East Asia, industrialization in the Philippines stagnated.
There are many reasons for the failure of industrialization to take off in the Philippines, which have been adequately discussed in other literature, among which are the political and economic instabilities in the Philippines in the 1970s. However, the pivot towards the provision of service labor to the global economy was among the reasons why manufacturing stagnated for a long time. The country’s labor migration policy came at the price of industrialization according to Masina (2026). The income and foreign exchange generated by labor migration reduced the incentive to build a competitive manufacturing base. With the emigration of workers, the labor supply thinned and remittances increased. Wages appreciated faster than productivity, leading to the decline in the number of manufacturers in the country. Furthermore, building an industrial base was capital intensive. It required the strategic mobilization of investments and investors, and demanded competitive advantage compared to other Southeast Asian countries. The Philippines, desperate for the economy to stay afloat, took the unconventional route by investing in labor export, more than strengthening the manufacturing industry and employment in the Philippines. While money from remittances could have been reinvested in export-manufacturing sectors like some Asian and Latin American countries did, remittances in the Philippines were invested by migrants and their families in consumer items, services, and real estate.
Corazon Aquino and succeeding administrations fortified the State’s labor export policy and industry. It was so successful that it produced what the Migration Policy Institute (2008) described as a scale of migration that is “unmatched elsewhere in the developing world.” The Philippine migration system managing temporary migration has further been described by the Migration Policy Institute as “unrivaled in sophistication” and is touted as “a model for other developing countries.” For years, the Philippine economy was buoyed by the billions of dollars sent home by its overseas contract workers. It provided employment for its highly educated population that could not be absorbed by the local job markets and has improved the incomes of numerous Filipinos. In other words, the Filipino migrant contingents have kept the economy afloat, contributing to the development of the Philippine economy and catapulting Filipino families to middle income status, despite the absence of an industrial base. Masina notes, the Philippine economy did not collapse, there was “no prolonged stagnation,” there was no “dramatic economic breakdown,” and “the economy stabilized.” This made emigration seem all the more an attractive and viable state employment and economic policy.
Despite the economic contributions of migration, progressive groups have been critical of the Philippine State’s migration policy, arguing that the migration-based national development policy has failed to develop the domestic economy. While South Korea, Taiwan, Malaysia, Thailand, and Vietnam built export-oriented manufacturing sectors that fortified their productivity, the growth of the Philippine economy, on the other hand, has largely been based on labor force entry and remittance-fueled consumption. Thus, the growth of the economy was characterized by low-productivity growth. The cracks in the migration policy as an economic development strategy became unmistakable with the onset of the global Covid pandemic. The pandemic forced more than two million overseas Filipino workers (OFWs) to return home, negatively affecting the Philippine economy. Migrant repatriation and the closure of foreign labor markets rudely awakened Philippine officials to the fragility of migration as a growth strategy given its vulnerability to global shocks. While the remittances remained high, the inability of the government to generate jobs for repatriated workers exposed the limits of migration as a substitute for domestic employment. The overreliance on remittances and their contributions to the economy underscored the point that the Philippines has not succeeded in building its manufacturing base to serve as a more stable source of national income.
Pitfalls in the Semiconductor Industry
The semiconductor industry in the Philippines started as early as the 1970s with the relocation of the back-end manufacturing of Fairchild, Intel, Texas Instruments, and Amkor in the Philippines, which made the Philippines an important electronics manufacturing hub in Asia. The operations of these companies in the country placed the Philippines in the global electronics supply chain, according to the OECD (2024). Through these years, the country’s semiconductor industry has been reliant on foreign direct investments, with US, South Korean, and Western European companies as the leading sources of the country’s investments and with a growing contingent of investments coming from Taiwan and Japan. Currently, the global tech giants that operate subsidiaries in the Philippines include American tech companies Texas Instruments, onsemi, Analog Devices, and Amkor Technology; European companies STMicroelectronics and Nexperia; and South Korea’s SFA Semicon.
These FDIs have brought the Philippines billions of dollars in investments. Moreover, a large percentage of the country’s commodity exports are semiconductor products, placing the Philippines in 9th place among semiconductor exporters in the world, according to an OECD Report (2024). Despite this, this has not translated to industrialization. Manufacturing in the country has, in fact, been disparagingly described as “shallow,” with limited links to domestic suppliers and industries (Piedad, 2026).
The Philippines remains at the tail-end of the global supply chains, given that the local industry players are only involved in Assembly, Testing, and Packaging (ATP), instead of high value, upstream or even midstream production. Upstream production involves knowledge-intensive production, while mid-stream production involves fabrication. These two phases are where most of the profits in the industry go. Upstream production is monopolized by big global players like the US, the UK, Taiwan, South Korea, and China. In Southeast Asia, Singapore joins the ranks of the mid-stream fabricators such as Taiwan, South Korea, and China. Southeast Asian countries like Malaysia, the Philippines, Thailand, and Vietnam are all concentrated in downstream production, with Malaysia cornering the largest market share in the region. The Philippines has only provided labor-driven value instead of the knowledge and capital-driven values provided by upstream and midstream producers in the global value chain. Sadly, the Philippines is losing its competitive edge to Malaysia and Vietnam, despite its involvement in the industry for half a century.
While the country has hosted semiconductor multinational giants for the last 50 years, no technology transfer has happened that would allow the Philippines to move up the production line. When Intel closed its operations in the Philippines after 35 years of operation, the country never benefited from technological transfer that would have enabled it to set up a homegrown local electronics industry (Jarabe, 2026; Africa, 2026). Texas Instruments has also kept its operations confined to ATP instead of investing in higher value production, since the 1970s (Africa, 2026). Of the 33 semiconductor corporations operating in the Philippines, only two are Filipino-owned (Jarabe, 2026). This limited domestic ownership underscores the weakness of the country’s semiconductor industry and supports the criticism that it has produced only shallow industrialization. Moreover, products produced in the country are low end products that other countries can easily produce, according to Bing Viera, who is the chair of the Semiconductor and Electronics Industries in the Philippines Foundation, Inc. Rather than fostering a robust industrial base of locally owned firms, the industry has remained heavily dependent on foreign investment, which means profits remain concentrated in the hands of multinational corporations, who chart the directions of their companies.
The failure of the State to employ state-led development strategies has led to a foreign-investment focused economic strategy. This is in stark contrast to the industrialization strategies of countries like South Korea, which has focused on building and supporting homegrown industries, instead of relying on foreign direct investments. South Korea selectively restricted foreign investment by multinational corporations and carried out technology importation and reverse engineering to prop up its national industries. Other countries in the region have also followed similar strategies, by carrying out nationalist planning in transforming their countries into manufacturing hubs. In contrast, the semiconductor industry in the Philippines has not served as a catalyst to build other local companies to support production (Aldaba and Aldaba, 2010). FDI spillover effects to domestic firms have been deficient because of the weak competitiveness of local firms and their inability to absorb technology or knowledge transfer. The export-processing model also created enclaves where manufacturers imported materials, used available local labor, and exported their goods after production, which left little room for domestic partnerships.
Prospects and Potential Pitfalls for Industrialization
Having missed industrialization opportunities in the past with its misplaced State policies and the absence of a coherent industrial strategy, the Philippines finds itself in a pivotal moment in its economic history, especially with the rapid changes in the global trade and global value chains over the last decade or so. Realizing the importance of industrialization to ensure sustained economic growth, President Benigno Aquino III and his successors set out clearer industrialization agendas. Aquino, for instance, laid down “The Comprehensive National Industrial Strategy (CNIS),” integrating “manufacturing, agriculture, and services; addressing supply chain gaps; and deepening industry participation in global value chains.” The Duterte Government later launched the Inclusive Innovation Industrial Strategy, which picked up some of the aims of the CNIS and more. The Marcos Jr. Government, on the other hand, passed the Tatak Pinoy Act in 2024 and then launched the Tatak Pinoy Strategy in 2025, an ambitious program that would run from 2025 to 2040 that seeks to align government and private sector efforts to improve the global competitiveness of Philippine industries, fostering the upward movement of local industries in the global value chain, and aiding local companies to offer diverse and sophisticated products and services.
저자 소개
아르니 코르데로 트리니다드(Arnie Cordero Trinidad, actrinidad@up.edu.ph)는
필리핀대학교 딜리만 사회학과 부교수다. 더블린 트리니티 칼리지에서 사회학 박사학위를 받았다. 현재 유럽연구위원회(European Research Council)의 지원을 받는 ‘희소금속 시대의 녹색 산업정책(Green Industrial Policy in the Age of Rare Metals, GRIP-ARM)’ 프로젝트에 참여하고 있다. 이주, 재난 관리, 핵심광물, 산업화에 관한 연구를 수행해 왔다. Sociology, European Societies, International Journal of Disaster Risk Reduction 등 주요 국제학술지에 논문을 발표했다.
Arnie Cordero Trinidad (actrinidad@up.edu.ph)
is an associate professor at the Department of Sociology, University of the Philippines Diliman. He has a doctorate in Sociology from Trinity College Dublin. He is currently involved in a European Research Council-funded project Green Industrial Policy in the Age of Rare Metals (GRIP-ARM). He has done research on migration, disaster management, critical minerals, and industrialization. He has published in top international journals such as Sociology, European Societies, and International Journal of Disaster Risk Reduction.
참고문헌
Africa, Sonny. 2026. “Pax Silica: Whose Industrialization Is It Anyway?” IBON Foundation, August 12, 2026. https://www.ibon.org/en/pax-silica-whose-industrialization-is-it-anyway/.
Aldaba, Rafaelita M., and Fernando T. Aldaba. 2010. “Do FDI Inflows Have Positive Spillover Effects? The Case of the Philippine Manufacturing Industry.” Philippine Journal of Development 37 (2). https://pjd.pids.gov.ph/site/volume-issue-view?id=22082.
Balaoing-Pelkmans, Annette. 2026. “Pax Silica and the Philippine Industrial Upgrading Challenge.” UPSE Discussion Paper [2026-06]. Quezon City: University of the Philippines School of Economics. https://pre.econ.upd.edu.ph/upsedp/index.php/dp/article/download/1573/1061.
Geducos, Argyll Cyrus and Hernando-Malipot, Merlina. 2026 “Pax Silica: What US seeks, what Philippines may offer, and where interests converge.” Manila Bulletin, https://mb.com.ph/2026/09/29/pax-silica-what-us-seeks-what-philippines-may-offer-and-where-interests-converge?hl=en-GB
Jarabe, Luisa Gabriela. 2026. “Jobs and Pax Silica: The Song Remains the Same.” IBON Foundation, June 27, 2026. https://www.ibon.org/jobs-and-pax-silica/.
Masina, Pietro. 2026. “Why the Philippines Never Became Vietnam: Remittances, migration, and growth without industrializing.” https://pietromasina.substack.com/p/why-the-philippines-never-became
Migration Policy Institute. 2008. “Lessons from the Philippines: MPI Releases Report on Unique Temporary Migration Management System.” Press release, October 7, 2008. https://www.migrationpolicy.org/news/lessons-philippines-mpi-releases-report-unique-temporary-migration-management-system.
OECD. 2024. Promoting the Growth of the Semiconductor Ecosystem in the Philippines. Paris: OECD Publishing. https://www.oecd.org/en/publications/promoting-the-growth-of-the-semiconductor-ecosystem-in-the-philippines_01497fea-en.html.
Piedad, Maricar. 2026. “The Curious Case of Philippine Manufacturing.” IBON Foundation, April 23, 2026. https://www.ibon.org/en/the-curious-case-of-ph-manufacturing/.
Williamson, Jeffrey G., and Emmanuel S. de Dios. 2014. “Has the Philippines Forever Lost Its Chance at Industrialization?” Philippine Review of Economics 51(2):47-66. https://pre.econ.upd.edu.ph/index.php/pre/article/view/909.
Zapanta, Logan Kal-El. 2026. “Philippines’ Semiconductors Sector Risks Stagnation.” Philippine Daily Inquirer. https://business.inquirer.net/577167/ph-chip-sector-risks-stagnation.
